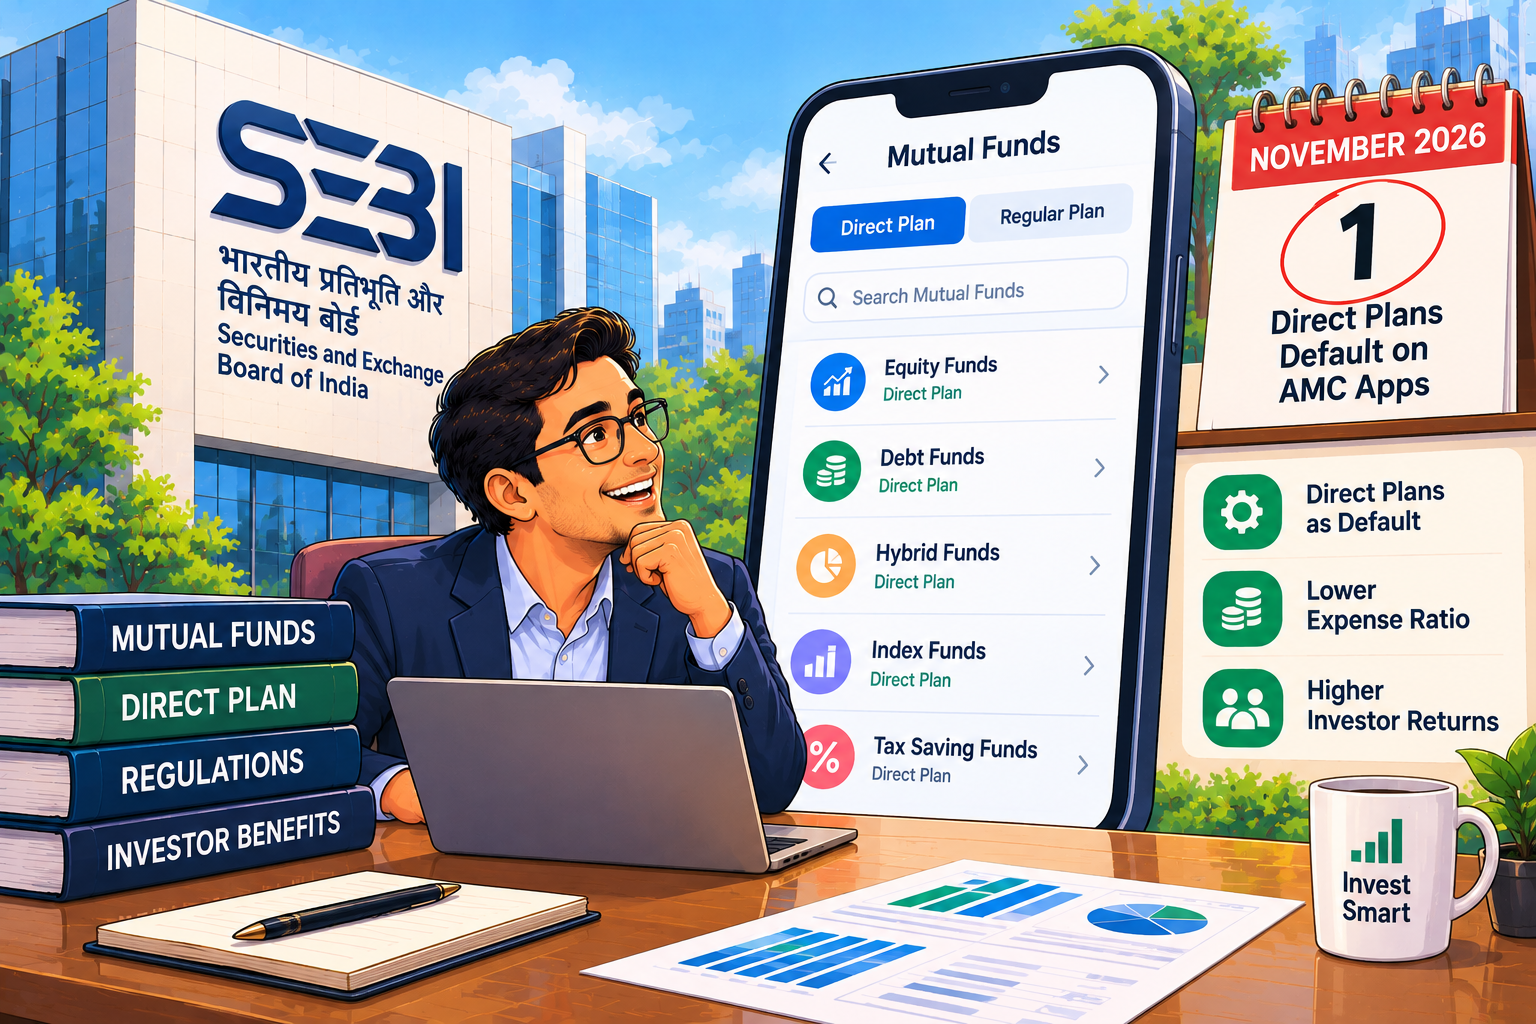
SEBI Chairman Tuhin Kanta Pandey has said that direct mutual fund plans will become the default option on the digital platforms of asset management companies (AMCs) from November 1, 2026. Investors who choose a regular plan on these platforms must be told about its higher expense ratio. Pandey made the announcement at a markets event in Mumbai on October 28.
What SEBI Said About Direct Plans on October 28
Pandey spoke about the regulator’s efforts to strengthen investor protection and improve transparency around mutual fund costs. He said protection also depends on how well investors are informed, and the direct plan default formed part of his remarks on that theme.
From Sunday, November 1, 2026, a direct plan will be the option shown first when an investor starts a purchase on an AMC’s app or website. An investor who still prefers the regular plan can choose it, but the platform must inform that investor of its higher expense ratio.
| Item | Detail |
|---|---|
| Announced by | SEBI Chairman Tuhin Kanta Pandey |
| Announcement date | October 28, 2026 |
| Effective date | November 1, 2026 |
| Applies to | Digital platforms of AMCs |
| Regular plan buyers | Must be informed of the higher expense ratio |
Direct Plans vs Regular Plans: Where the Cost Difference Comes From
A direct plan lets an investor buy units straight from the AMC without going through a mutual fund distributor. Direct plans are available on AMC websites and other permitted direct-investment channels, where investors can choose schemes, start systematic investment plans (SIPs) or make lump-sum investments and then monitor their portfolios on their own. Because there is no distributor commission, the total expense ratio (TER) of a direct plan is lower than that of the regular plan of the same scheme. TER is the annual cost, shown as a percentage of the fund’s assets, that is deducted from the scheme to cover its running expenses.
Regular plans are bought through intermediaries such as distributors, banks or financial advisers, and the commissions paid to them are built into the expense ratio. These intermediaries may assist with scheme selection, transactions and other investment-related services. Both plans of a scheme invest in the same underlying portfolio under the same fund manager, with the same investment objective and risk profile. The difference lies in the cost of distribution.
The table below shows what a 0.5 percentage point gap in the annual expense ratio would mean in rupees. The figures are illustrative. They assume the investment value stays unchanged for a year, and the real gap differs from scheme to scheme.
| Amount invested (₹) | Extra yearly cost at a 0.5 percentage point higher expense ratio (₹) |
|---|---|
| 1,00,000 | 500 |
| 5,00,000 | 2,500 |
| 10,00,000 | 5,000 |
Over longer periods, even small cost differences reduce the amount that stays invested and earns returns. A lower expense ratio, however, does not remove market risk and does not guarantee better performance.
What the November 1 Default Changes and What It Leaves Open
The announcement comes as more Indian households invest in mutual funds through SIPs and digital platforms. It is specific, and several practical questions are not answered in what has been said publicly so far.
- The default applies to the digital platforms of AMCs. It does not establish that independent investment platforms will adopt the same default.
- Regular plans remain available as a choice, but the investor must be informed of the higher expense ratio.
- The announcement does not specify how existing investments will be treated.
- A direct plan comes without a distributor to help with choosing or monitoring schemes, so the investor handles that part alone.
Starting a SIP After November 1: What to Check
Many investors begin their SIPs through apps. Anyone planning to start SIP online on an AMC platform after November 1 will see the direct plan first, so it helps to confirm the plan name on the screen before the first instalment is set up.
Compare the expense ratios of the direct and regular options of the same scheme, not of different schemes. Different schemes follow different strategies and carry different risks, so a cost comparison across them says little.
Investors who prefer to hold units in demat form, rather than in a statement of account, need a demat account. They can open demat account online with a depository participant and then use an investing platform of their choice to monitor holdings.
Should Existing Regular Plan Investors Switch?
Switching from a regular plan to the direct plan of the same scheme generally means redeeming units in the regular plan and buying units in the direct plan. The redemption can trigger capital gains tax and an exit load, depending on the investment and how long it has been held.
A lower expense ratio can lift net returns marginally over the long term, assuming everything else stays equal, but it is only one input in the decision. Direct plans may suit investors who understand mutual funds, can judge their own risk appetite and goals, and are comfortable selecting and monitoring schemes without help. Regular plans may suit those who value assistance with scheme selection, transactions and portfolio monitoring, provided they understand the extra cost and the services they receive in return.
Read Mutual Funds Related Blogs
- What is NFO (New Fund Offer)?
- What are Hedge Funds?
- What are Opportunity Funds?
- What is NAV in Mutual Fund?
- Investing in S&P 500 Stocks via Index Funds
Leave a Reply